|
|
Home Select
The Sunday
Notebook
No. 18 · Sunday 20 September 2026
|
||||||||||||
|
||||||||||||
|
01 · The editorial
This week, the European Central Bank raised its rates by a quarter of a point. The move was expected. The news did not lead the Sunday papers, and yet it is quietly closing a lending window that has been open for the past year. The Paris buyer watches his rate like a thermometer. He notes the 0.11-point rise over the month, calculates what it changes in his monthly repayment, hesitates at times. The vendor looks at something else: the number of months his property has been sitting on the market. Two clocks are ticking in parallel, and the second matters to our trade more than the first. This Sunday's article is devoted to that gap. It sheds light, we believe, on what is really at stake in Paris at the September 2026 rentrée. |
||||||||||||
|
||||||||||||
|
|
||||||||||||
|
02 · Article of the week
Buyers watch the rate, vendors watch the calendar
Credit · Negotiation · 6 min read
|
||||||||||||
|
||||||||||||
|
||||||||||||
|
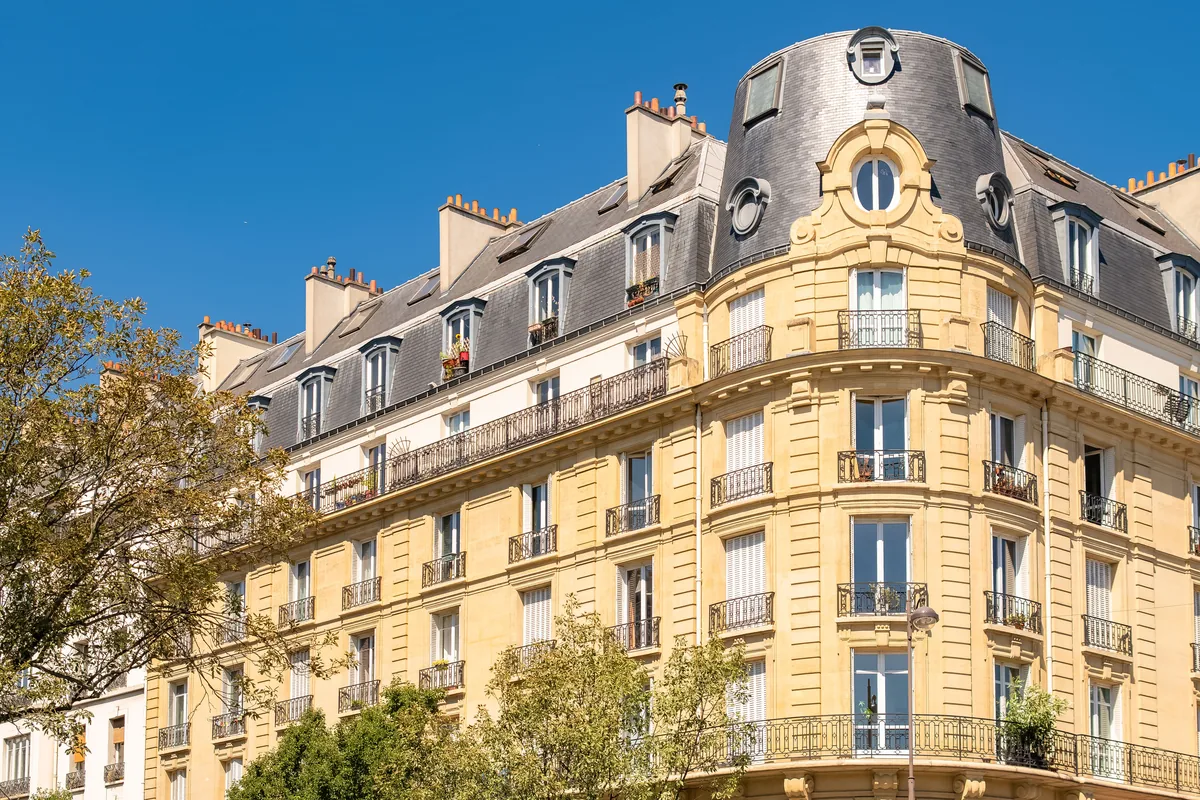
The ECB raised its rates on 10 September. Mortgage rates edged up by a few hundredths. In Paris, the real variable of adjustment lies elsewhere. On 10 September 2026, the European Central Bank raised its key rates by a quarter of a point, taking the deposit rate to 2.50%, its highest since March 2025. The second rise of the year, after June's. Eurozone inflation reached 3.3% in August, against 2.9% in July, and Brent crossed $100 a barrel the day before the decision. The ECB justified the move by the persistence of the energy shock and by lasting price pressures. On the mortgage market, the pass-through is real but measured. Average September rates stand at 3.43% over fifteen years, 3.54% over twenty and 3.61% over twenty-five, according to Pretto. Meilleurtaux records slightly lower schedules: 3.28%, 3.40% and 3.50% over the same terms. The monthly rise runs at 0.11 to 0.12 point. This is no earthquake. The mechanics rest on a factor that is little commented upon: the French ten-year OAT, which serves as the benchmark for the cost of bank funding, has crossed the 4% mark, a level not seen since 2009. Empirically, a twenty-year fixed-rate loan trades around the OAT plus 150 basis points. The autumn schedules bear the imprint. For a buyer, the arithmetic reads as follows. On a €200,000 loan over twenty years, an extra quarter of a point represents about €25 more per month, or a little over €6,000 across the full term of the loan, according to Pretto's calculations. A variable to factor in, not trivial, but one that does not fundamentally change the equation of a Paris project. The usury rate for fixed-rate loans of twenty years and more stands at 5.29% in the third quarter of 2026, with a revision expected on 1 October: the banks retain room to manoeuvre. In Paris, another parameter weighs more heavily. Transactions rose meaningfully in the second quarter of 2026 compared with 2025, according to observations reported at the rentrée. The rebound is real, even if a low comparison base explains part of it. Above all, the pickup has not played out on the same terms across the board. Properties well positioned in the spring have sold. Those that missed the window are lingering, and their owners are beginning to count the months. This is where the real negotiation is played out. Take an order of magnitude. The average price per square metre in Paris stood at €9,670 on 1 September 2026, within a wide range from €6,538 to €16,252 depending on the area (MeilleursAgents). On a Paris property at €800,000, three per cent negotiated represents €24,000. Set that against the €6,000 in extra cost across the full term of the loan mentioned above. The balance is not in doubt: the margin is made at the point of purchase, not at the tenth of a point on the rate. Our hunters observe it week after week: properties that have passed the four-month mark on the market negotiate more openly. The vendor who turned down an offer in the spring watches his property linger in September; the rentrée has not delivered the hoped-for lift, and the autumn looks less favourable. That shift is quiet. It does not make the headlines, but it transforms the conversation a well-prepared hunter can open with the listing agent. A nuance is in order. This reading applies to the ordinary market, which remains the bulk of Paris transactions. It does not apply to the rare, the highly sought after, the exceptional property whose window is measured in days. On those, the buyer remains the suitor, negotiation stays marginal, and the mortgage rate reverts to a secondary parameter. Groupe BPCE forecasts 890,000 transactions in the existing-property market in 2026: the statistic is made on the mainstream market. What the credit rentrée teaches us, in the end, is that a Paris project is better prepared than it is optimised. Consolidating one's deposit, clarifying one's borrowing capacity, choosing one's intermediary, framing one's search: these gestures weigh more heavily on the final price than daily surveillance of the ten-year OAT. |
||||||||||||
|
Average mortgage rates in September 2026
|
||||||||||||
|
||||||||||||
|
||||||||||||
|
||||||||||||
|
||||||||||||
|
03 · Buyer's advice
Secure your borrowing capacity before viewingAn up-to-date agreement in principle from your bank, obtained before the first viewings, is worth more than an online simulation. It pins down your real envelope, reassures the vendor at the point of offer, and allows your hunter to negotiate with the weight of a file ready to sign. Obtenir un crédit immobilier à Paris › |
||||||||||||
|
||||||||||||
|
||||||||||||
|
See you next Sunday.
In the meantime, if a project is taking shape, we remain at your disposal for an initial conversation. We assess your brief against the market and deliver an unvarnished reading.
|
|
Home Select
Property hunters since 2011
|
|||||
|
|||||
|
60 rue François 1er, 75008 Paris · 01 78 76 78 10 Member of the Federation of Property Hunters (FCI) |
|||||
|
|
|||||
|
You are receiving this email because you shared your contact details with Home Select as part of a property project or an information request. Under the General Data Protection Regulation (GDPR), you have rights of access, rectification, erasure, objection, portability and restriction over the data concerning you. To exercise these rights, write to contact@homeselect.paris.
Data controller: Jean Mascla, Home Select, 60 rue François 1er, 75008 Paris. Your data is kept for three years after our last contact, then deleted. In case of disagreement, you may lodge a complaint with the CNIL (www.cnil.fr). |
|||||
|
© 2026 Home Select. All rights reserved.
|