|
|
Home Select
The Sunday
Notebook
No. 14 · Sunday 23 August 2026
|
||||||||||||
|
||||||||||||
|
01 · The editorial
This week, an arithmetical exercise rather than a stance. For eighteen months, a portion of our clients have deferred their Paris project, resting more or less consciously on two cumulative bets: rates would fall, prices would follow. Both deserve re-examination in the light of the spring and summer figures. We make no claim to settle the matter. We observe three concurring signals: the average mortgage rate has climbed back to 3.30% in July, the 10-year OAT briefly crossed 4%, and Paris apartment prices are holding firm at €9,520 per square metre. These signals change the nature of waiting: long neutral, sometimes productive, it now carries a measurable cost. This week's article details that cost, without prescription. Waiting remains a legitimate position, provided one makes explicit what one is waiting against. |
||||||||||||
|
||||||||||||
|
|
||||||||||||
|
02 · Article of the week
Waiting to buy in Paris: the calculation has changed
Financing · Trade-off · 5 min read
|
||||||||||||
|
||||||||||||
|
||||||||||||
|
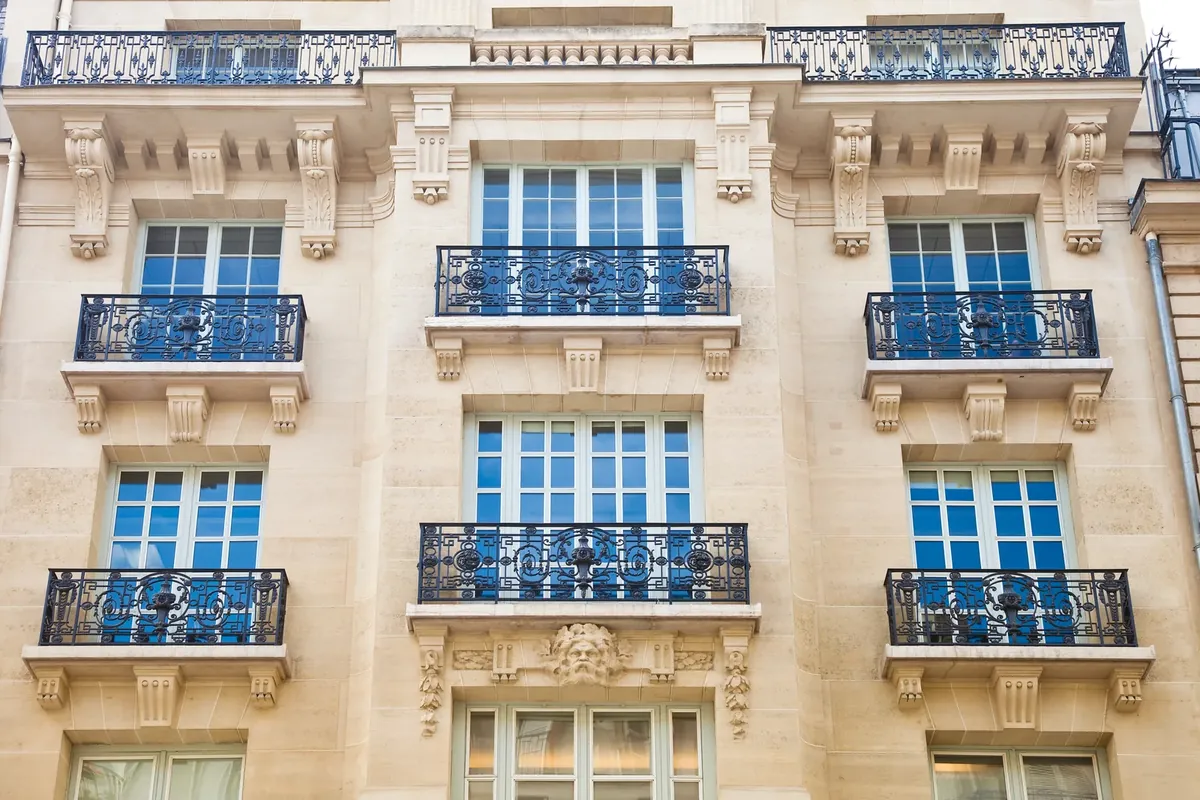
For two years, deferring a Paris purchase rested on an implicit thesis: rates would fall, prices too. The summer of 2026 undermines both assumptions at once. What seemed neutral is now a bet, with figures to prove it. The case for waiting rested on a chronology that had become familiar. The European Central Bank, having begun a cutting cycle in 2024, was expected to press on. Mortgage rates, dragged down in its wake, would restore purchasing power to buyers. Paris prices, judged high, would eventually give way. Three links in a single chain of reasoning, taken as read by a portion of the market. The first link broke in June. On 11 June 2026, the ECB raised its three key rates by 25 basis points, bringing the deposit facility rate to 2.25%. This was the first increase since 2023, following a cutting cycle begun a year earlier. The rationale sits in a single figure: eurozone inflation reached 3.2% in May, its highest level since September 2023. A pause was observed on 23 July, but swap markets now price in roughly two further 25-basis-point hikes by the end of the year. On mortgage rates, the indicator that matters is not the ECB but the 10-year OAT. Its yield briefly exceeded 4% on 23 July, against 3.65% at the start of the month. Banks did not immediately pass on this move, but their room to keep cutting their grids has narrowed. The average rate on mortgages taken out in July stands at 3.30%, up 4 basis points on the month and 22 basis points from the low of 2025. The Observatoire Crédit Logement/CSA envisages a trajectory towards 4% by the end of 2027. The second link, that of Paris prices, is holding. The Notaires du Grand Paris publish a price for existing apartments of €9,520 per square metre for March-May 2026, up 0.1% year-on-year. At the end of April, the reading stood at €9,530, or +0.4% annually. One may debate the margin of error on such figures; one cannot read into them the correction that was expected. Sales volumes in the Île-de-France are down 3% over February-April compared with 2025, but this modest retreat is largely explained by an early 2025 inflated by anticipation of the rise in transfer taxes. The arithmetic of waiting then writes itself simply. By way of illustration, a buyer who was borrowing €600,000 over twenty years at 3.08% a year ago had a monthly repayment of around €3,340. At 3.30% today, at a constant monthly repayment, the borrowable capital falls by about €14,000 according to a standard annuity calculation. Put differently, waiting twelve months more, at unchanged Paris prices, amounts to financing an apartment shorn of a studio of equivalent surface at the same average price. The average loan duration in France, now 253 months according to the Observatoire Crédit Logement, only marginally offsets this effect. Our point is not that one must buy. It is that waiting, long neutral in cost, no longer is. The question posed to a buyer in observation mode is no longer 'when' but 'against what'. Against a scenario of falling rates that presupposes a marked retreat of inflation and an ECB pivot that markets are not pricing. Against a scenario of falling Paris prices that the notaires do not document, in a market where volumes are holding and where the supply of quality properties remains tight. Choosing to wait on an explicit thesis remains legitimate. Doing so by default, tacitly rolling over the 2024-2025 assumption, warrants review. That is the sole message of this letter: to make the terms of the trade-off visible, so that the decision to wait, if it is taken, is taken in full knowledge of its cost. |
||||||||||||
|
Borrowing €600,000 over twenty years, a year ago and today
|
||||||||||||
|
||||||||||||
|
||||||||||||
|
||||||||||||
|
||||||||||||
|
03 · Buyer's advice
Separating the purchase decision from the financing decisionA buyer who has identified their property can lock in their rate from the moment they receive an offer in principle, independently of the signing timetable. This dissociation, still too rare, protects against a sharp move in bank grids between the preliminary agreement and the final deed. Sécuriser son financement en 2026 › |
||||||||||||
|
||||||||||||
|
||||||||||||
|
See you next Sunday.
In the meantime, if a project is taking shape, we remain at your disposal for an initial conversation. We assess your brief against the market and deliver an unvarnished reading.
|
|
Home Select
Property hunters since 2011
|
|||||
|
|||||
|
60 rue François 1er, 75008 Paris · 01 78 76 78 10 Member of the Federation of Property Hunters (FCI) |
|||||
|
|
|||||
|
You are receiving this email because you shared your contact details with Home Select as part of a property project or an information request. Under the General Data Protection Regulation (GDPR), you have rights of access, rectification, erasure, objection, portability and restriction over the data concerning you. To exercise these rights, write to contact@homeselect.paris.
Data controller: Jean Mascla, Home Select, 60 rue François 1er, 75008 Paris. Your data is kept for three years after our last contact, then deleted. In case of disagreement, you may lodge a complaint with the CNIL (www.cnil.fr). |
|||||
|
© 2026 Home Select. All rights reserved.
|