|
|
Home Select
The Sunday
Notebook
No. 3 · Sunday 7 June 2026
|
||||||||
|
||||||||
|
01 · The editorial
The European Central Bank meets on 11 June. After twelve months of monetary stasis, a quarter-point rise is no longer a fringe scenario: it is now the market's central expectation. For a Paris buyer in the middle of weighing options, the sequence deserves attentive reading, without haste. We have looked closely this week at what the decision actually changes, and what it does not. The answer takes only a few lines. The current window, around 3.50% over twenty years, will probably not open any wider before the autumn. It may, on the other hand, close by one notch. Our conviction is unchanged. A quarter of a point does not make an acquisition decision. It accelerates or delays its execution. The maturity of the project, the quality of the property, the precision of the negotiation weigh infinitely more in the balance sheet of a transaction than twenty-five basis points on the headline rate. |
||||||||
|
||||||||
|
|
||||||||
|
02 · Article of the week
What a quarter of a point really changes
Rates · Analysis · 5 min read
|
||||||||
|
||||||||
|
||||||||
|
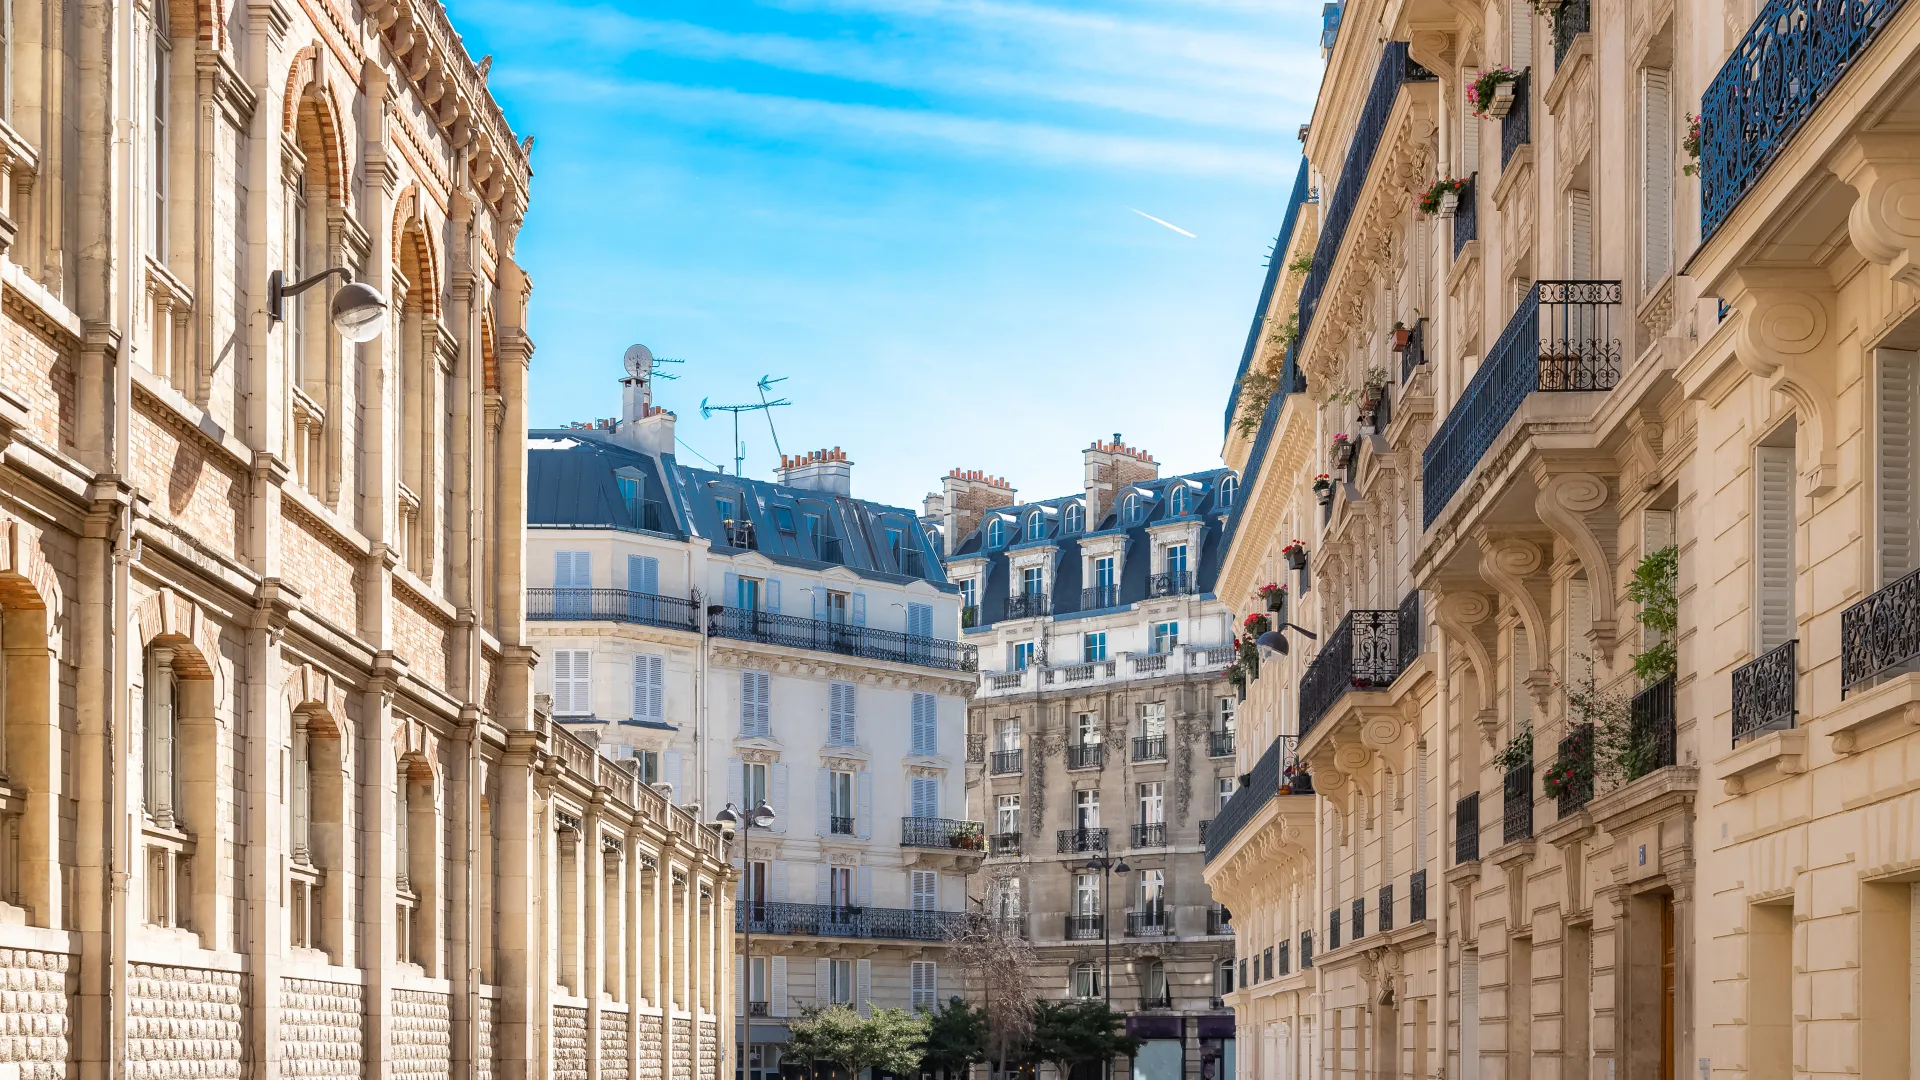
On 11 June, the ECB is expected to raise its deposit rate after a year of immobility. For the Paris buyer, the mechanics are less spectacular than the headlines suggest, but the consequences can be measured. A composed reading of a sequence that closes a window without opening anything catastrophic. The European Central Bank has held its main policy rate at 2% for a year. Eurozone inflation reached 3% in April, its highest level since September 2023, and the institution's chief economist, Philip Lane, has indicated that inflation projections will be revised upwards in June. Isabel Schnabel, the German member of the Executive Board, has spoken plainly in an interview with Reuters: standing still is no longer an option in her view, and a rise in June seems to her necessary. Markets now price in two twenty-five basis point increases before year-end. Economists polled by Reuters anticipate the same sequence, followed by a cut in 2027. How that decision transmits to mortgage lending is another matter. The channel is not direct. Banks calibrate their fixed-rate lending grids primarily by reference to the ten-year OAT, the rate at which the French state borrows. That indicator saw a notable tension in May: it briefly crossed 4% on 20 May, a level not seen since 2009, before easing back to around 3.55% on 29 May according to Trading Economics. The ECB's decision weighs on the OAT through anticipation, but the OAT also leads a life of its own, tethered to French sovereign debt and to the temper of international investors. On the ground, the average rates recorded in June by Pretto stand at 3.37% over fifteen years, 3.47% over twenty years and 3.53% over twenty-five years. Cafpi publishes slightly lower grids for the strongest files, between 3.25% and 3.55% depending on duration. These levels reflect a stabilisation after several months of mild creep upwards. Guillaume Fourt, at Meilleurtaux, warns that no sharp decline is expected before the September rentrée; Ludovic Laborde, co-founder of Eloa, adds that future borrowers should not wait for a massive fall in rates. If the ECB confirms its move on 11 June, certain scenarios floated by brokers deserve to be taken seriously without being taken as gospel. PAP suggests that borrowing at 3.80% in October can no longer be ruled out, and that signing today at 3.50% might avoid an unpleasant surprise in the autumn. We remain cautious in the face of such extrapolations: thirty basis points of increase over four months implies a rapid transmission that is far from automatic. The direction of travel is nevertheless clear, and the opposite scenario, a significant easing before the autumn, now appears extinguished. In concrete terms, what does a quarter of a point represent on a loan? On a 250,000 € credit over twenty years, moving from 3.20% to 3.47% adds 34 € to the monthly instalment and 8,254 € to the total cost of the loan, according to figures supplied by the brokers at Eloa. Transposed to a higher Paris borrowing, the order of magnitude remains proportional. Twenty-five additional basis points do not ruin a viable transaction. They can, however, tip a borderline file into bank refusal, or eat into the deposit capacity of a buyer financing at the tightest margin. The Paris market itself is showing no signs of wait-and-see. The Notaires du Grand Paris record a 7% rise in sales in Paris over the year, in a wider Île-de-France market up 11%. Prices stand at 9,570 € per square metre for second-hand Paris apartments in January, up 1% over twelve months. In the first quarter, stabilisation is confirmed at the regional level, with a contained progression of 0.6%. Pretto also reports a 6% rise in mortgage production in the first quarter of 2026; Meilleurtaux speaks of around 10% over the year. The market is turning over. This is not the moment of an exceptional window, it is the moment of a sustainable equilibrium. Our reading dispenses with drama. For anyone holding an accepted offer and negotiating their financing, signing in June on the current grids appears reasonable. For anyone with a mature project, a solid file and an identified property, waiting out of tactical calculation carries the risk, as brokers remind us, of seeing prices rise in the meantime. For anyone still hesitating about the property itself, twenty-five basis points should not become the argument that rushes a poorly weighed decision. The property comes before the rate. Always. |
||||||||
|
What a quarter of a point costs on a €250,000 loan over twenty years
|
||||||||
|
||||||||
|
||||||||
|
||||||||
|
||||||||
|
03 · Buyer's advice
Securing your financing before the compromisIn a context where lending grids shift between the accepted offer and signature, ask your broker or your bank for a simulation at the current grid, not at last month's. This precaution avoids unpleasant surprises when the loan offer is drawn up. A few days' delay can sometimes be enough to reshuffle the cards. Read this week's advice › |
||||||||
|
||||||||
|
||||||||
|
See you next Sunday.
In the meantime, if a project is taking shape, we remain at your disposal for an initial conversation. We assess your brief against the market and deliver an unvarnished reading.
|
|
Home Select
Property hunters since 2011
|
|||||
|
|||||
|
60 rue François 1er, 75008 Paris · 01 78 76 78 10 Member of the Federation of Property Hunters (FCI) |
|||||
|
|
|||||
|
You are receiving this email because you shared your contact details with Home Select as part of a property project or an information request. Under the General Data Protection Regulation (GDPR), you have rights of access, rectification, erasure, objection, portability and restriction over the data concerning you. To exercise these rights, write to contact@homeselect.paris.
Data controller: Jean Mascla, Home Select, 60 rue François 1er, 75008 Paris. Your data is kept for three years after our last contact, then deleted. In case of disagreement, you may lodge a complaint with the CNIL (www.cnil.fr). |
|||||
|
© 2026 Home Select. All rights reserved.
|